Platform
1Adults who manage their own capital often wonder how to allocate across three markets when the choices feel as different as Manhattan towers, Tel Aviv towers, and Kyiv redevelopment zones. Foundation publishes plain guidance so non-experts can weigh those contrasts without needing a finance degree. The following sections unpack the practical questions that surface first.
Opening Questions Every New Allocator Asks
1Minimum Investment Thresholds at Foundation before drafting any plan.
Many first-time cross-border investors also wonder how long capital must stay committed. Holding periods vary by asset type and local regulations, so the honest answer is to treat each market’s typical cycle as its own calendar rather than forcing a single exit date across all three. That habit prevents forced sales when one location slows while another still offers rent growth.
New York Office and Residential Pull Factors
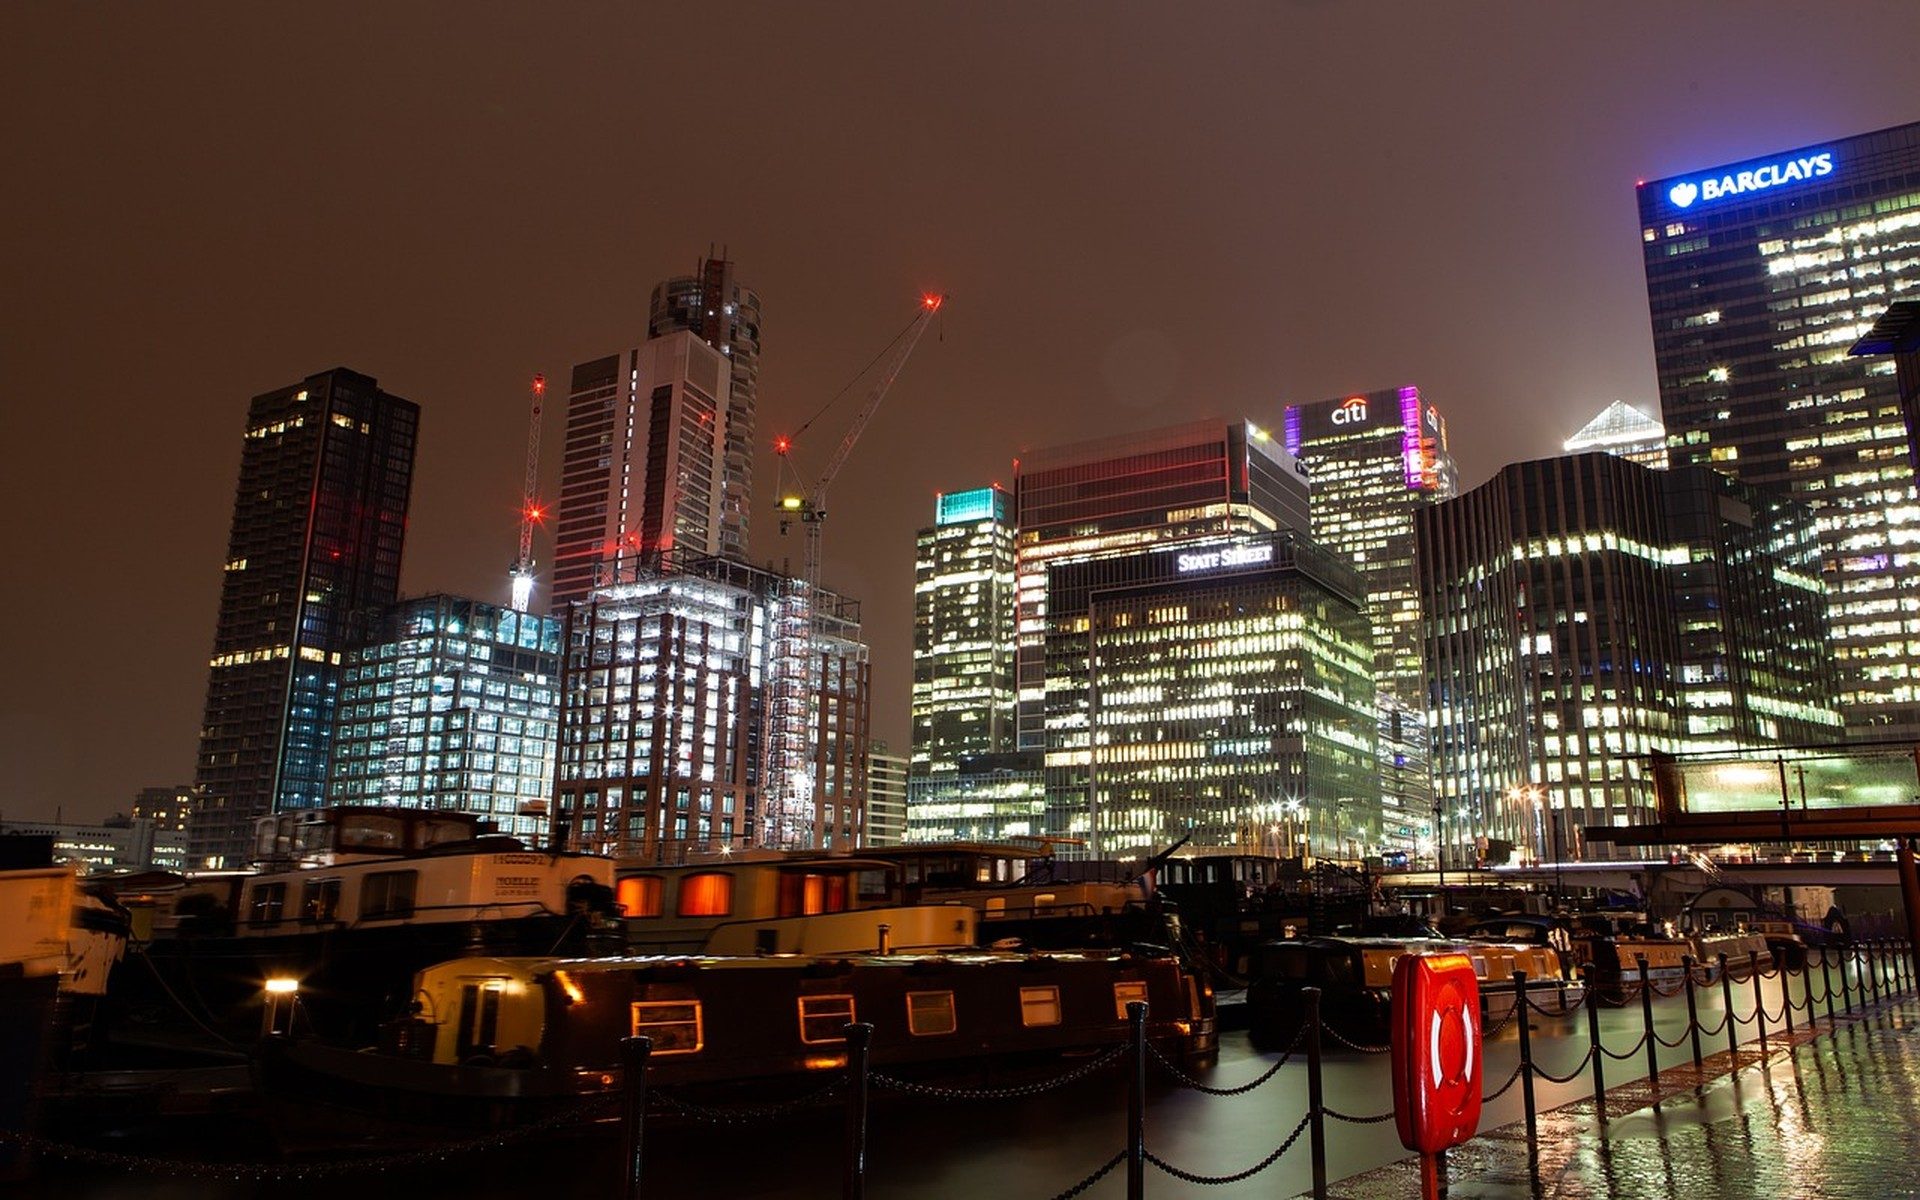
1Manhattan and selected borough pockets continue to draw capital because of deep tenant demand, transparent title records, and ready secondary markets. Institutional ownership remains high, which can stabilize prices yet also means individual tickets may start larger than elsewhere. When an investor assigns a New York slice, the decisive variables are usually subway proximity, building age after capital improvements, and the ratio of long leases versus short-term occupancy. Global rate decisions published by the US Federal Reserve influence mortgage costs and cap rates here more quickly than in the other two locations, so checking those releases becomes part of ordinary homework.
Trophy assets in prime corridors often behave differently from mid-market stock; side-by-side contrasts appear in the dedicated piece Comparing Trophy Real Estate in New York, Israel and Ukraine. Reading that comparison helps decide whether a New York allocation should lean luxury or worker housing.
Israel’s Tech-Linked Property Patterns
1Israel’s coastal cities and inland tech campuses show stronger ties to high-skill employment than pure tourism or commodity cycles. Vacancy rates in well-located office parks tend to track venture funding waves and defense-export orders. Residential demand near research universities and military campuses stays resilient even when national growth slows. Currency risk is present because rental income is frequently denominated in shekels while many foreign investors report in dollars; a modest currency hedge or simply holding a smaller shekel-exposed share can keep the overall portfolio calmer.
Investors who want regular updates can follow the Foundation Quarterly Market Intelligence Brief for district-level absorption figures without wading through raw government tables. Those briefs also flag shifts in foreign-buyer rules so timing of new purchases stays informed rather than reactive.
Ukraine Rebuild and Income-Generating Niches
1Ukraine’s property story after 2022 contains both reconstruction demand and continuing operational risk. Western and central regions that host logistics corridors and agricultural processing plants have attracted quieter private capital than front-line areas. Warehouse and residential projects that serve displaced workers or returning families can generate rental yields that outpace many Western peers, yet title verification and insurance costs remain higher. Allocators usually keep the Ukraine slice smaller and longer-dated than the New York or Israel portions until insurance markets and local banking services fully reopen.
Public data sets from the World Bank and country pages within International Monetary Fund publications supply independent growth forecasts that help size the Ukraine exposure. Foundation itself does not publish those macro tables; instead it points investors toward the original sources so they can form their own view.
Percentages That Reflect Real Risk Tolerance
1A workable starting matrix for many private investors looks roughly like 50 percent New York for ballast, 30 percent Israel for growth linkage, and 20 percent Ukraine for higher yield with longer patience. Those numbers are examples only; someone who lives in New York may already hold excess local real estate and therefore invert the weights. Someone whose business already concentrates in Israeli technology may deliberately lighten the Israel property sleeve. The guiding principle is simple: every added percentage in one market should reduce a percentage somewhere else so total exposure never exceeds the cash and sleep threshold the household has set.
Cross-border spreadsheets also need a line for unexpected transaction costs. Legal fees, currency conversion, and local notary charges can add several points to the purchase price in any of the three jurisdictions. Building a 3, 5 percent buffer into each allocation keeps the intended percentages from slipping once cash actually moves.
Sources Worth Checking Before Money Moves
1Beyond Foundation material, independent authorities offer free context that any adult can read. The Bank for International Settlements tracks global credit conditions that eventually reach property markets. Reading one of its quarterly reviews alongside local vacancy data gives a more complete picture than either source alone. Inside Foundation’s own site, the rolling collection of articles under the News Hub and the longer history inside the News archive show how past allocation decisions fared when conditions changed.
People who prefer short answers can begin at the general FAQ (frequently asked questions) page, which links onward to specialized topics without forcing a full research deep-dive. Those resources stay free of sales pressure so readers can decide for themselves whether a three-market split fits their circumstances.